Mississippi Wastewater Treatment Plants
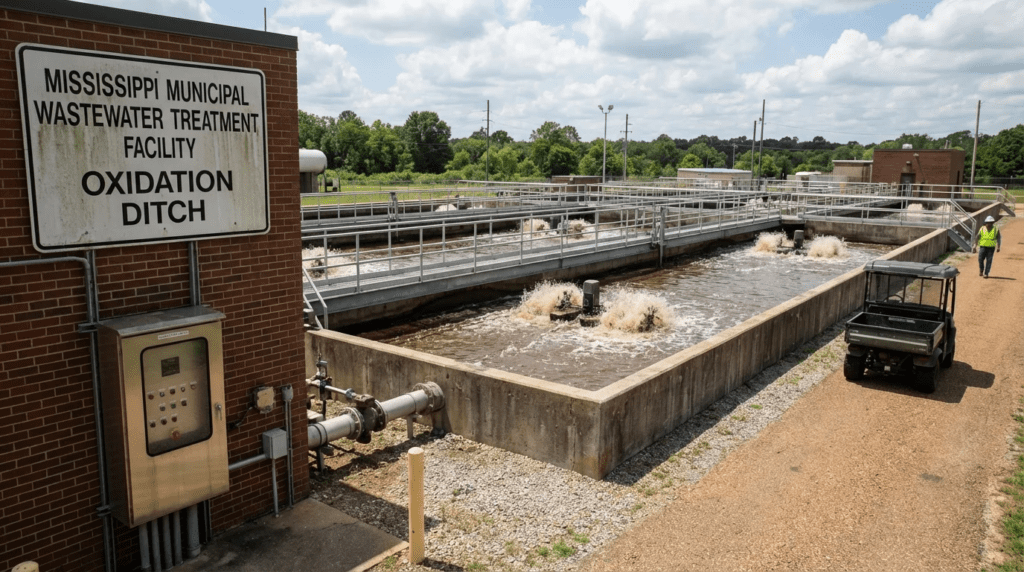
1. Overview of Mississippi’s Wastewater Infrastructure
Mississippi’s wastewater infrastructure landscape represents a critical intersection of historical municipal challenges and unprecedented modern investment. Regulated primarily by the Mississippi Department of Environmental Quality (MDEQ) under the purview of EPA Region 4, the state oversees hundreds of publicly owned treatment works (POTWs) ranging from small rural lagoon systems to major regional mechanical plants.
Currently, the state’s total treatment capacity exceeds 350 million gallons per day (MGD), serving a population of nearly 3 million residents. However, Mississippi faces profound infrastructure hurdles. Severe inflow and infiltration (I/I) exacerbated by the region’s expansive Yazoo clay soils, historical underinvestment, and stringent enforcement of Sanitary Sewer Overflow (SSO) regulations have pushed many municipalities to their operational limits.
To combat these issues, the state is undergoing a massive revitalization era. Through a combination of the Clean Water State Revolving Fund (CWSRF), the Bipartisan Infrastructure Law (IIJA), and the Mississippi Municipality and County Water Infrastructure (MCWI) Grant Program, billions of dollars are being injected into the sector. For municipal consulting engineers, utility managers, and equipment vendors, Mississippi currently offers one of the most active wastewater overhaul markets in the Southeast United States.
This state directory forms part of our national inventory of US wastewater treatment plants, which lets engineers and suppliers compare capacity, process configuration, and capital activity across state lines.
2. Recent Developments & Infrastructure Projects
The last three years have marked a paradigm shift in how Mississippi funds and manages its wastewater treatment plants. The most high-profile development is the ongoing receivership and stabilization of Jackson’s water and wastewater systems. Managed by JXN Water under a federally appointed third-party administrator, the city’s Savanna Street Wastewater Treatment Plant is seeing fast-tracked capital injections to correct decades of deferred maintenance and environmental compliance issues.
Beyond the capital city, the state legislature’s creation of the MCWI program allocated $450 million in American Rescue Plan Act (ARPA) funds to be matched dollar-for-dollar by local municipalities, effectively creating nearly $1 billion in water and wastewater project volume between 2022 and 2026. This has mobilized engineering firms across the state to design system upgrades, lift station rehabilitations, and treatment capacity expansions.
Innovation is also taking root. Many legacy municipal lagoon systems are actively being converted to mechanical activated sludge plants or advanced moving bed biofilm reactor (MBBR) systems to meet stricter MDEQ nutrient limits. Coastal regions, managed by authorities like the Harrison County Utility Authority (HCUA) and Jackson County Utility Authority (JCUA), are deploying climate resilience strategies to harden their facilities against Gulf hurricanes and storm surges. Meanwhile, public-private partnerships and progressive design-build contracts are becoming increasingly common mechanisms to expedite critical consent-decree-driven overhauls.
Operations Transition at Jackson’s Wastewater System
The operating arrangement behind Jackson’s plants changed materially in late 2025 and is worth understanding, because it is the largest single O&M contract in the state. Veolia had operated the city’s wastewater treatment facilities and pump stations for roughly nine years. In November 2025, JXN Water awarded a nine-year operations and maintenance contract to Jacobs, structured as an amendment to the water services contract Jacobs already held for the O.B. Curtis and J.H. Fewell water plants. The wastewater agreement covers Jackson’s three wastewater treatment plants and 99 pump stations. Stated near-term priorities under the new contract are completing a comprehensive condition assessment, implementing a strategic improvement plan aimed at restoring reliability and preventing bypasses, and transitioning existing staff while supporting operator certification to address the shortage of qualified personnel. For vendors and consulting firms, the practical implication is that the procurement path into Jackson’s wastewater capital program now runs through a single integrated water and wastewater operator rather than two separate contracts.
3. Top 20 Largest Wastewater Treatment Plants in Mississippi
Below is a ranked list of Mississippi’s 20 largest wastewater treatment plants by design capacity, based on EPA ECHO data, MDEQ permitting, and municipal utility reports.
| Rank | Plant Name | City/Location | Design Capacity (MGD) | Population Served | Operating Authority |
|---|---|---|---|---|---|
| 1 | Savanna Street WWTP | Jackson | 46.0 MGD | 200,000 | JXN Water |
| 2 | Gulfport North WWTP | Gulfport | 15.0 MGD | 75,000 | Harrison County Utility Authority |
| 3 | DeSoto County Regional WWTP | Southaven | 14.0 MGD | 85,000 | DCRUA |
| 4 | Tupelo Water Reclamation Plant | Tupelo | 12.0 MGD | 50,000 | Tupelo Water & Light |
| 5 | Meridian WWTP | Meridian | 11.5 MGD | 45,000 | City of Meridian |
| 6 | West Jackson County WWTP | Ocean Springs | 10.5 MGD | 40,000 | Jackson County Utility Authority |
| 7 | Hattiesburg South WWTP | Hattiesburg | 10.0 MGD | 48,000 | City of Hattiesburg |
| 8 | Greenville WWTP | Greenville | 9.5 MGD | 30,000 | City of Greenville |
| 9 | Vicksburg WWTP | Vicksburg | 8.5 MGD | 22,000 | City of Vicksburg |
| 10 | Pascagoula-Gautier WWTP | Pascagoula | 8.0 MGD | 35,000 | JCUA |
| 11 | Starkville WWTP | Starkville | 7.5 MGD | 30,000 | Starkville Utilities |
| 12 | Oxford WWTP | Oxford | 7.0 MGD | 35,000 | City of Oxford |
| 13 | Columbus WWTP | Columbus | 6.5 MGD | 25,000 | Columbus Light & Water |
| 14 | Biloxi East WWTP | Biloxi | 6.0 MGD | 25,000 | Harrison County Utility Authority |
| 15 | Clinton South WWTP | Clinton | 5.5 MGD | 25,000 | City of Clinton |
| 16 | Pearl WWTP | Pearl | 5.0 MGD | 26,000 | City of Pearl |
| 17 | Olive Branch Regional WWTP | Olive Branch | 4.5 MGD | 40,000 | City of Olive Branch |
| 18 | Natchez WWTP | Natchez | 4.0 MGD | 15,000 | Natchez Water Works |
| 19 | Clarksdale WWTP | Clarksdale | 3.5 MGD | 15,000 | Clarksdale Public Utilities |
| 20 | McComb WWTP | McComb | 3.0 MGD | 13,000 | City of McComb |
Detailed Profiles: Top 5 Largest Facilities
Savanna Street Wastewater Treatment Plant – Rank #1
- Location: Jackson, Hinds County, MS
- Design Capacity: 46.0 MGD (Peak Flow: ~100+ MGD)
- Current Average Flow: 35.0 MGD
- Population Served: ~200,000 residents
- Operating Authority: JXN Water (Third-Party Administrator)
- Receiving Water: Pearl River
- Service Area: City of Jackson and surrounding Hinds County areas
Treatment Process: Preliminary (bar screens, grit removal), Primary (clarification), Secondary (activated sludge), Tertiary (UV disinfection replacing historical chlorine systems).
Infrastructure: Biosolids are managed via anaerobic digestion and belt filter press dewatering. Odor control is actively being upgraded at the headworks.
Recent Upgrades/Notable Features: Currently undergoing massive federally mandated overhauls under JXN Water. Upgrades include complete replacement of primary clarifier mechanisms, massive UV system rehabilitation, and sludge handling facility modernization.
Compliance & Performance: Operating under a stringent EPA Consent Decree to eliminate SSOs and bypass events. Significant progress has been made since 2022 in stabilizing effluent quality.
The plant is the single most consequential facility in the state and the subject of the longest-running Clean Water Act enforcement action in Mississippi. The consent decree was entered in late 2012, with a roughly 18-year compliance horizon and the bulk of the injunctive work nominally due within the first eleven years; the city has since estimated full implementation at a cost far above the original projection. Bypass volumes tell the operational story more plainly than any compliance summary: roughly 4.5 billion gallons of untreated or partially treated wastewater reached the Pearl River from Savanna Street over a two-year window spanning 2020 to 2022. Our full profile of the Jackson publicly owned treatment works covers the Savanna Street process train, the decree obligations, and the rehabilitation program in detail.
Link: Savanna Street WWTP Page
Gulfport North WWTP – Rank #2
- Location: Gulfport, Harrison County, MS
- Design Capacity: 15.0 MGD
- Current Average Flow: 10.2 MGD
- Population Served: ~75,000 residents
- Operating Authority: Harrison County Utility Authority (HCUA)
- Receiving Water: Biloxi River
- Service Area: Northern Gulfport and Harrison County
Treatment Process: Advanced secondary treatment (oxidation ditches), secondary clarification, and UV disinfection. Nutrient removal capabilities optimized for sensitive coastal waterways.
Recent Upgrades: Hardened infrastructure against Category 4 hurricane storm surges; comprehensive SCADA system integration.
Link: Gulfport North WWTP Page
DeSoto County Regional WWTP – Rank #3
- Location: Southaven, DeSoto County, MS
- Design Capacity: 14.0 MGD
- Current Average Flow: 9.5 MGD
- Population Served: ~85,000 residents
- Operating Authority: DeSoto County Regional Utility Authority (DCRUA)
- Receiving Water: Mississippi River Tributary (Horn Lake Creek)
Treatment Process: Activated sludge, continuous flow, followed by filtration and disinfection.
Recent Upgrades: Multiple expansion phases to accommodate massive residential growth spilling over from the Memphis metropolitan area.
Tupelo Water Reclamation Plant – Rank #4
- Location: Tupelo, Lee County, MS
- Design Capacity: 12.0 MGD
- Current Average Flow: 7.8 MGD
- Population Served: ~50,000 residents
- Operating Authority: Tupelo Water & Light
- Receiving Water: Town Creek
Treatment Process: Advanced activated sludge with biological nutrient removal (BNR), tertiary filtration, and UV disinfection.
Recent Upgrades: Comprehensive $12M biosolids handling upgrade and digester cleanout completed recently to improve energy recovery and reduce disposal costs.
Meridian WWTP – Rank #5
- Location: Meridian, Lauderdale County, MS
- Design Capacity: 11.5 MGD
- Current Average Flow: 7.0 MGD
- Population Served: ~45,000 residents
- Operating Authority: City of Meridian
- Receiving Water: Sowashee Creek
Treatment Process: Conventional activated sludge.
Compliance & Performance: The plant is the focal point of a major EPA consent decree. The city is executing multi-million dollar rehabilitation plans to address I/I and plant capacity constraints during wet weather events.
Condensed Listing (Ranks 6-20)
Large Regional Plants (Rank 6-10)
- West Jackson County WWTP – Ocean Springs: 10.5 MGD capacity, serves 40,000 people. Operated by JCUA. Features advanced hurricane resilience.
- Hattiesburg South WWTP – Hattiesburg: 10.0 MGD capacity, serves 48,000 people. Operated by City of Hattiesburg. Transitioning from major lagoon system.
- Greenville WWTP – Greenville: 9.5 MGD capacity, serves 30,000 people. Operated by City of Greenville. Active consent decree compliance program.
- Vicksburg WWTP – Vicksburg: 8.5 MGD capacity, serves 22,000 people. Operated by City of Vicksburg. Discharges to the Mississippi River.
- Pascagoula-Gautier WWTP – Pascagoula: 8.0 MGD capacity, serves 35,000 people. Operated by JCUA.
Major Municipal Plants (Rank 11-15)
- Starkville WWTP – Starkville: 7.5 MGD capacity. Supports Mississippi State University population flux.
- Oxford WWTP – Oxford: 7.0 MGD capacity. Undergoing aggressive expansions due to Ole Miss campus growth.
- Columbus WWTP – Columbus: 6.5 MGD capacity. Operated by Columbus Light & Water.
- Biloxi East WWTP – Biloxi: 6.0 MGD capacity. Highly specialized coastal nutrient removal.
- Clinton South WWTP – Clinton: 5.5 MGD capacity. Recently expanded.
Significant Facilities (Rank 16-20)
- Pearl WWTP – Pearl: 5.0 MGD capacity. Important Jackson metro relief facility.
- Olive Branch Regional WWTP – Olive Branch: 4.5 MGD capacity. Rapidly growing DeSoto County suburb.
- Natchez WWTP – Natchez: 4.0 MGD capacity. Historic bluff city discharging to the Mississippi River.
- Clarksdale WWTP – Clarksdale: 3.5 MGD capacity. Essential Delta region infrastructure.
- McComb WWTP – McComb: 3.0 MGD capacity. Southern MS hub.
4. Plants with Approved Budgets & Expansion Projects
Mississippi is experiencing a historic boom in water infrastructure construction. Driven by EPA consent decrees, available IIJA funding, and the state MCWI ARPA match program, millions of dollars are flowing into the heavy civil and environmental engineering sectors.
A. MAJOR PROJECTS UNDER CONSTRUCTION (2024-2026)
Savanna Street WWTP – $45 Million Phase 1 Rehabilitation Project
- Location: Jackson, Hinds County
- Project Scope: Extensive rehabilitation of headworks, primary clarifiers, biosolids dewatering facility, and ultraviolet (UV) disinfection systems. Capacity optimization to handle peak wet-weather flows of 100+ MGD.
- Total Budget: $45 million (Phase 1 of multi-phase $200M+ program)
- Funding Breakdown:
- Federal Direct Appropriations: $25 million
- SRF / IIJA Grants: $20 million
- Timeline:
- Design completed: May 2023
- Construction start: September 2023
- Expected completion: December 2025
- Technology Upgrades: Installation of new high-efficiency bar screens, advanced UV reactor banks, and modernized SCADA controls.
- Project Drivers: Federal EPA Consent Decree, Safe Drinking Water Act/Clean Water Act emergency compliance, aging infrastructure.
- Key Contractors: Design Engineer: Jacobs / Waggoner Engineering; General Contractor: Hemphill Construction.
- Expected Benefits: Eradication of bypass events into the Pearl River, massive reduction in effluent TSS and BOD.
Hattiesburg South Mechanical Plant – $45 Million Lagoon Conversion
- Location: Hattiesburg, Forrest County
- Project Scope: Complete transition from a traditional lagoon treatment system to a state-of-the-art mechanical activated sludge facility.
- Total Budget: $45 million
- Funding Breakdown: 50% State ARPA Match ($22.5M), 50% Local Revenue Bonds ($22.5M)
- Timeline: Construction start: Early 2024; Expected completion: Mid-2026
- Technology Upgrades: Aeration basins, secondary clarifiers, mechanical sludge dewatering centrifuges.
- Project Drivers: Compliance with stringent MDEQ nutrient limits and eliminating land-intensive lagoon footprint.
Meridian WWTP – $30 Million Consent Decree Compliance Phase
- Location: Meridian, Lauderdale County
- Project Scope: Major wet-weather flow management upgrades, equalization basin construction, and clarifier rehabilitation.
- Total Budget: $30 million
- Funding Breakdown: 80% SRF Loan ($24M), 20% Local Funds ($6M)
- Project Drivers: EPA Consent Decree, elimination of SSOs.
- Current Status: 40% complete.
B. PROJECTS IN DESIGN/PLANNING PHASE (2025-2027)
- Greenville WWTP – Facility Rehabilitation: Estimated budget: $25 million. Funding: Pending SRF/ARPA match. Scope: Major equipment overhaul mandated by consent decree. Expected construction start: 2025.
- Oxford WWTP – Capacity Expansion: Estimated budget: $15 million. Funding: Local Revenue Bonds. Scope: Expansion from 7 MGD to 9 MGD to support university population growth. Expected start: Late 2025.
- JCUA West Jackson Consolidation: Estimated budget: $20 million. Funding: IIJA grant allocations. Scope: Lift station and force main routing to consolidate smaller rural plants into the regional facility.
- Starkville WWTP – BNR Upgrade: Estimated budget: $12 million. Funding: State SRF. Scope: Biological Nutrient Removal upgrades to meet new effluent criteria.
C. RECENTLY COMPLETED MAJOR PROJECTS (2022-2024)
- Tupelo Water Reclamation Plant – Biosolids Upgrade (Completed Nov 2023)
- Investment: $12 million
- Key improvements: Anaerobic digester cleanout, new belt filter presses.
- Results achieved: 40% reduction in biosolids hauling costs.
- Clinton South WWTP – Treatment Expansion (Completed Jan 2024)
- Investment: $8.5 million
- Key improvements: Added secondary treatment capacity.
- Results achieved: Compliant with new municipal growth limits.
- DCRUA Ross Road WWTP – Expansion (Completed 2022)
- Investment: $18 million
- Key improvements: Expanded from 2 MGD to 4 MGD capacity for Southaven sprawl.
SUMMARY STATISTICS
- Total Active Capital Investment: ~$350 million currently under construction state-wide
- Number of Plants with Major Active Projects: 18 facilities
- Total New Capacity Being Added: ~45 MGD optimized/added across MS
- Largest Single Project: Savanna Street WWTP (Jackson) – $45M (Phase 1)
- Primary Project Drivers:
- Consent decrees: 5 projects ($120 million)
- Aging infrastructure/Lagoon conversions: 8 projects ($150 million)
- Capacity expansion: 5 projects ($80 million)
- Funding Source Breakdown:
- State/Federal ARPA (MCWI): $150 million (43%)
- State Revolving Fund (SRF): $110 million (31%)
- Revenue Bonds: $50 million (14%)
- Federal IIJA Grants: $40 million (12%)
INDUSTRY IMPLICATIONS
The influx of IIJA and ARPA funding has created a lucrative environment for engineering firms and equipment vendors in Mississippi. There is immense demand for heavy-duty pump manufacturers, UV disinfection system providers, and SCADA integrators. Furthermore, the push away from lagoon systems means mechanical equipment vendors are finding a rapidly expanding market for aeration blowers, diffusers, and mechanical dewatering equipment.
5. Regulatory & Compliance Landscape
The Mississippi Department of Environmental Quality (MDEQ) acts as the primary enforcement arm for the EPA’s Clean Water Act in the state. MDEQ issues National Pollutant Discharge Elimination System (NPDES) permits and sets state-specific water quality standards. Currently, the state is undergoing a significant regulatory shift regarding nutrient criteria. To combat hypoxia in the Gulf of Mexico, inland plants discharging into the Mississippi River basin and coastal plants are facing stricter Total Nitrogen (TN) and Total Phosphorus (TP) limits.
A dominant theme in Mississippi’s regulatory landscape is the use of federal Consent Decrees. Major municipalities, including Jackson, Greenville, and Meridian, are operating under these decrees to eliminate Sanitary Sewer Overflows (SSOs). These decrees mandate strict, legally binding schedules for sewer line inspections, lift station rehabilitations, and WWTP capacity upgrades.
Furthermore, MDEQ is beginning to implement monitoring requirements for Per- and Polyfluoroalkyl Substances (PFAS) in municipal biosolids and effluent, aligning with emerging federal EPA standards. This is anticipated to drive future tertiary treatment and advanced filtration upgrades across the state’s top 20 plants over the next decade.
Gulf Hypoxia and Basin-Scale Nutrient Reduction
Mississippi occupies an unusual regulatory position: it is both a contributor to and a recipient of nutrient loading from a basin draining thirty-one states. The seasonal hypoxic zone that forms off the Louisiana and Mississippi coast each summer is driven overwhelmingly by nitrogen and phosphorus delivered down the Mississippi River, which means a plant in Vicksburg or Natchez discharging to the river sits inside a nutrient reduction framework that reaches far beyond MDEQ’s jurisdiction. The Hypoxia Task Force coordinates state nutrient reduction strategies across the basin, and while these have historically been implemented through voluntary agricultural measures rather than binding point-source limits, the direction of travel for municipal permits is toward numeric nutrient criteria. Utilities in Louisiana face the same dynamic at the receiving end of the basin, and engineers benchmarking a Mississippi BNR retrofit will often find the closest operating analogues among Gulf coast plants in that state rather than among inland systems elsewhere in the Southeast.
The Consent Decree Environment and What It Means for Design
Consent decrees change how projects are scoped, procured, and defended, and Mississippi has enough of them that engineers working here should understand the mechanics. A decree converts what would ordinarily be a discretionary capital plan into a court-enforceable schedule with milestone dates, stipulated penalties for missed deadlines, and required reporting to EPA and the Department of Justice. That has three practical consequences for design. First, schedule risk outranks cost optimization, which favors delivery methods that compress design and construction. Second, scope tends to front-load assessment work — flow monitoring, CCTV inspection, hydraulic modeling — because the decree requires the utility to demonstrate the basis for its remedy rather than simply build one. Third, decrees frequently outlive the political and staff tenure of the utility that signed them, which is why documentation continuity and asset data quality matter more here than on ordinary capital work. Jackson’s decree, entered in 2012 with roughly an eighteen-year compliance horizon, illustrates all three points, and comparable long-running municipal SSO decrees across the Gulf South — including several in Alabama — offer the closest procedural precedents for utilities entering negotiation.
6. Infrastructure Challenges & Opportunities
Mississippi engineers and operators face unique geographical and socioeconomic challenges. The most notorious is the state’s geology—specifically, the “Yazoo Clay” prevalent in the central part of the state. This highly expansive soil shrinks and swells dramatically with moisture changes, causing severe shearing and breaking of underground sewer mains. This leads to catastrophic Inflow and Infiltration (I/I) during Mississippi’s heavy rainy seasons, flooding WWTP headworks and causing bypasses.
Economically, many rural Mississippi utility districts lack the tax base to afford necessary multimillion-dollar mechanical upgrades. This has created an opportunity for regionalization—consolidating small, failing package plants and lagoons into larger regional authorities like the JCUA or DCRUA.
Another pressing challenge is workforce development. Like much of the nation, Mississippi faces a critical shortage of Class IV certified wastewater operators. This gap is driving a major opportunity for automation and smart water technologies. Municipalities are actively seeking SCADA upgrades, remote monitoring sensors, and AI-driven predictive maintenance software to operate facilities effectively with leaner crews.
The DeSoto County Growth Corridor
Mississippi’s fastest-growing wastewater market is not driven by anything happening inside Mississippi. DeSoto County sits directly beneath the Memphis metropolitan area, and the residential growth filling Southaven, Olive Branch, Horn Lake, and Hernando is metro-Memphis growth crossing a state line. That produces a demand profile unlike anywhere else in the state: sustained, predictable, subdivision-driven capacity additions rather than the rehabilitation-and-consent-decree work dominating central and western Mississippi. DCRUA has responded with a regional model, expanding capacity in phases and consolidating what would otherwise be a scatter of small package plants serving individual developments. Engineers and vendors evaluating this corridor should treat it as part of the Memphis market rather than the Mississippi market, since growth projections, developer expectations, and competitive dynamics follow conditions in Tennessee. The corresponding risk is a mirror of the opportunity: capacity built against subdivision forecasts is exposed if the metro growth rate slows, which argues for modular phasing over single large expansions.
Lagoon Conversion Economics
The statewide shift away from facultative lagoons deserves closer examination than a technology trend line suggests, because the conversion decision is rarely straightforward. Lagoons are cheap to operate, tolerate erratic loading, and require modest operator attention, which is precisely why they proliferated across rural Mississippi. What they cannot do is meet numeric nutrient limits, control algae-driven TSS excursions in warm months, or fit inside the shrinking land envelopes of growing municipalities. Conversion to a mechanical plant typically raises operating cost several-fold — energy for aeration, chemicals, sludge handling, and a higher operator certification class — against a capital cost that a small utility usually cannot fund without state or federal participation. The result is that conversion decisions in Mississippi are effectively driven by grant availability rather than by lifecycle analysis. Utilities that model post-conversion OPEX honestly during the funding application, and set rates accordingly before the new plant is commissioned, avoid the pattern where a grant-funded facility becomes an unaffordable operating liability three years after ribbon-cutting.
7. Technology Trends in Mississippi
As Mississippi modernizes, specific treatment technologies are gaining rapid adoption. The most prominent trend is the phase-out of traditional facultative lagoons. Municipalities are replacing them with Activated Sludge variations, including Sequencing Batch Reactors (SBRs) and Moving Bed Biofilm Reactors (MBBR), which offer smaller footprints and superior nutrient removal.
In the disinfection space, there is a massive statewide transition away from gaseous chlorine toward UV Disinfection and peracetic acid (PAA), driven by operator safety concerns and strict chlorine residual limits in NPDES permits.
Biosolids handling is also modernizing. Due to rising landfill costs, plants like Tupelo are investing heavily in advanced dewatering (centrifuges and screw presses) to increase dry solids cake percentage. Coastal plants are actively exploring energy resilience technologies, including backup natural gas generators and elevated electrical/SCADA rooms to protect critical controls from hurricane storm surges.
A quieter but consequential trend is the spread of collection system instrumentation. Because so much of Mississippi’s compliance exposure originates in the pipes rather than at the plant, utilities under decree obligations are deploying permanent flow meters, level sensors at known overflow points, and rainfall-derived I/I analytics rather than relying on periodic manual flow studies. The data serves two purposes at once: it targets rehabilitation spending toward the basins actually contributing wet weather flow, and it produces the documentation record that decree reporting requires.
8. Complete Directory of Facilities
Browse our comprehensive directory of water and wastewater treatment plants in Mississippi, categorized by size:
Major Regional Facilities (>10 MGD)
- Savanna Street WWTP (Jackson)
- Gulfport North WWTP (HCUA)
- DeSoto County Regional WWTP
- Tupelo Water Reclamation Plant
- Meridian WWTP
- West Jackson County WWTP (JCUA)
- Hattiesburg South WWTP
Large Municipal Plants (5-10 MGD)
- Greenville WWTP
- Vicksburg WWTP
- Pascagoula-Gautier WWTP
- Starkville WWTP
- Oxford WWTP
- Columbus WWTP
- Clinton South WWTP
- Pearl WWTP
Medium-Sized & Community Plants (<5 MGD)
- Olive Branch Regional WWTP
- Natchez WWTP
- Clarksdale WWTP
- McComb WWTP
- Plus over 100+ small municipal and lagoon systems statewide. View Full List
9. Resources for Engineers & Operators
For professionals working within Mississippi’s water infrastructure sector, the following resources are invaluable for certification, funding, and networking:
- Mississippi Water Environment Association (MWEA): The premier state organization for wastewater professionals, hosting the annual WEA conference. Visit Site
- Mississippi Department of Environmental Quality (MDEQ): Oversees operator certification, SRF funding applications, and NPDES permitting. Visit Site
- Mississippi Rural Water Association (MsRWA): Excellent resource for training, technical assistance, and compliance for smaller, rural lagoon and package plant systems. Visit Site
- State Operator Certification Program: Managed by MDEQ, offering study guides and testing schedules for Class I through IV wastewater operator licenses.
- EPA ECHO and Consent Decree Records: Permit limits, Discharge Monitoring Report history, inspection findings, and lodged consent decrees for Mississippi facilities are publicly retrievable and are the fastest way to verify a utility’s compliance posture before pursuing work.
10. Frequently Asked Questions (FAQ)
How many wastewater treatment plants are in Mississippi?
Mississippi has over 300 permitted municipal wastewater treatment facilities, ranging from major 40+ MGD mechanical plants to small rural facultative lagoon systems.
What are the 5 largest treatment facilities in Mississippi?
The top five by design capacity are the Savanna Street WWTP (Jackson – 46 MGD), Gulfport North WWTP (15 MGD), DeSoto County Regional WWTP (14 MGD), Tupelo WRP (12 MGD), and Meridian WWTP (11.5 MGD).
Which plants in Mississippi have major expansion projects underway?
Major active projects include Jackson’s Savanna Street ($45M Phase 1), Hattiesburg’s Lagoon Conversion ($45M), and Meridian’s Consent Decree wet weather upgrades ($30M).
What funding is available for treatment plant upgrades in Mississippi?
Primary funding sources include the Clean Water State Revolving Fund (CWSRF) managed by MDEQ, federal IIJA grants, and the ARPA-backed Mississippi Municipality and County Water Infrastructure (MCWI) grant program.
What treatment technologies are most common in Mississippi?
While historically dominated by facultative lagoons, Mississippi is rapidly transitioning to Activated Sludge (including SBRs and MBBRs). UV disinfection is quickly replacing traditional chlorine contact chambers.
How is Mississippi addressing PFAS contamination?
MDEQ is aligning with federal EPA directives, initiating monitoring and sampling programs for PFAS in municipal biosolids and effluent, which will inform future regulatory limits.
What are the operator certification requirements in Mississippi?
MDEQ requires municipal plants to be supervised by a certified operator. Certifications range from Class I (small lagoons) to Class IV (complex mechanical plants over 5 MGD). Certification requires a mix of education, experience, and passing a state board exam.
Which Mississippi treatment plants are under consent decrees?
Several major municipalities are currently operating under EPA consent decrees primarily due to Sanitary Sewer Overflows (SSOs). Notable examples include Jackson, Greenville, and Meridian.
What is the total capital investment in Mississippi wastewater infrastructure?
Currently, there is approximately $350 million in active WWTP capital construction state-wide, with over $1 billion in total water/wastewater need projected over the next decade.
Who operates Jackson’s wastewater treatment plants?
Program responsibility sits with JXN Water, the entity created when a federal court placed Jackson’s water and later its sewer operations under third-party management. Day-to-day operations and maintenance are performed under contract. Veolia held that contract for roughly nine years; in November 2025 JXN Water awarded a nine-year operations and maintenance agreement to Jacobs, covering Jackson’s three wastewater treatment plants and 99 pump stations as an amendment to the water services contract Jacobs already held. Because arrangements of this kind continue to evolve under court supervision, verify current status directly with JXN Water before relying on it for procurement decisions.
Why does Yazoo clay cause so much trouble for Mississippi sewer systems?
Yazoo clay is highly expansive: it swells when wet and shrinks when dry, and the resulting ground movement shears rigid pipe joints and cracks manhole structures. The failure mode is not a single break but widespread joint separation across an entire basin, which admits large volumes of groundwater and stormwater. That inflow and infiltration arrives at the plant as wet weather flow well beyond design, and when headworks and secondary capacity are exceeded the result is a bypass or an overflow upstream in the collection system. It is why Mississippi rehabilitation programs emphasize trenchless lining and joint sealing over spot repairs, and why flow monitoring is usually the first item funded under a consent decree.
11. Conclusion
Key Takeaways
- Compliance drives the capital program — Consent decrees at Jackson, Greenville, and Meridian convert capital planning into court-enforceable schedules, which reorders priorities toward schedule certainty over cost optimization.
- The problem is usually in the pipes — Yazoo clay shears sewer joints across whole basins, so wet weather flow rather than plant process failure is the root cause behind most bypass events in central Mississippi.
- Lagoon conversion is grant-driven, not lifecycle-driven — Mechanical plants raise operating cost several-fold. Utilities that fail to model post-conversion OPEX and set rates before commissioning inherit a facility they cannot afford to run.
- DeSoto County is a different market — Growth in the Memphis corridor is subdivision-driven and predictable, unlike the rehabilitation work dominating the rest of the state. Modular phasing hedges the metro growth risk.
- Nutrient limits will tighten from the basin down — Gulf hypoxia pressure means the direction of travel for river-discharging plants is toward numeric nutrient criteria, and BNR retrofit precedents are more likely to be found along the Gulf than inland.
- Verify Jackson before you quote it — Operating arrangements at the state’s largest system remain under court supervision and have changed more than once. Confirm current status rather than relying on any published summary.
Mississippi presents an unusually clear split between two kinds of work. West and central of the state, the market is rehabilitation: aging collection systems in expansive soils, long-running federal decrees, and plants whose capacity constraint arrives entirely during wet weather. Along the northern border and the Gulf coast, the market is growth and resilience: capacity for subdivisions crossing the Tennessee line, and hardening for storm surge along Harrison and Jackson counties. Both are funded, for now, by a convergence of ARPA, IIJA, and revolving fund money that will not repeat at this scale. The utilities that come out of this cycle in good shape will be the ones that spent it on assessment and asset data as well as concrete, and that set rates against the operating cost of what they built rather than the capital cost of what they were granted.